Portugal is currently the world's sixth largest producer of olive oil and the third largest European exporter, with a sector worth around 700 million euros and exports that exceeded one billion euros in the 2023 and 2024 seasons. A remarkable rise, built on decades of modernization of olive groves, investment in cutting-edge technology, and the transformative role of Alqueva in the Alentejo region.
Nevertheless, the sector faces a paradox: it produces more than 90% extra virgin olive oil – the best rate in the world – but continues to export a significant portion of its production in bulk, under foreign brands, without capturing the added value that the quality would justify. In an interview with Grande ConsumoManuel Norte Santo, president of ECLAC – The Center for Studies and Promotion of Olive Oil in Alentejo, takes stock of the 9th National Olive Oil Congress and outlines the path the sector needs to take: from artificial intelligence in olive groves to conquering the Indian market, passing through the construction of strong and differentiated Portuguese brands.
The olive oil sector today represents around 700 million euros, and Portugal is the sixth largest producer in the world and the third largest exporter in Europe. How did we get here? What were the determining factors in this structural transformation of the sector in recent decades?
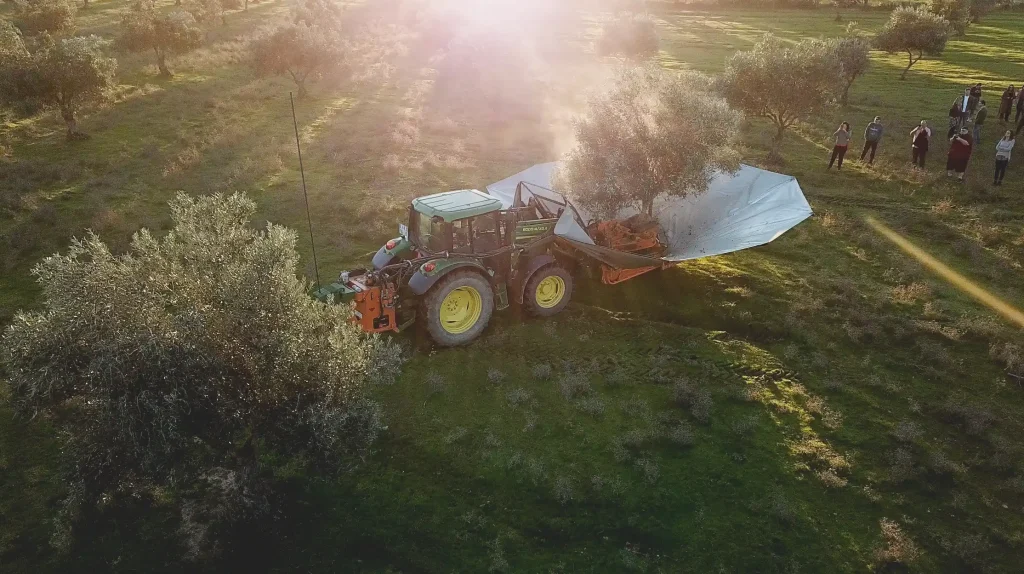
One of the main drivers of this evolution was the strong investment made in the modernization of olive groves and mills. Portugal is currently at the technological forefront of olive oil production, both agriculturally and industrially. The introduction of modern and hedgerow olive groves, efficient irrigation systems, mechanized harvesting, and innovative agronomic practices have allowed for very significant gains in productivity and quality.
Throughout this journey, the role of Alqueva was absolutely crucial. The availability of water provided by the Alqueva project profoundly transformed the productive capacity of the Alentejo region, creating conditions for large-scale investments. Alqueva brought water stability, competitiveness, and growth capacity, and is today one of the pillars of the international recognition of Portuguese olive oil.
“I believe the future lies in increasing the weight of exports under strong and differentiated Portuguese brands, capable of enhancing not only the product, but also the origin, quality, and identity of Portuguese olive oil. This evolution would allow for greater added value, reduce dependence on fluctuations in the international market, and make the sector less vulnerable to price volatility.”
Exports exceeded one billion euros in the 2023 and 2024 campaigns. The sector maintains a trade surplus of 92 million euros in the first two months of 2026, albeit with a lower volume traded. How do you interpret these figures? Are they a sign of maturity or of pressure on volumes?
I believe that these figures are, above all, a sign of the sector's maturity. The reduction in the value of exports in 2026 is primarily related to the drop in olive oil prices in international markets, following the exceptional levels recorded in recent years due to production shortfalls in several Mediterranean countries. As Portugal remains heavily dependent on bulk olive oil exports, it ends up being more exposed to the volatility of global prices.
It is precisely here that there is enormous growth potential for the Portuguese sector. Today we have productive capacity, recognized quality and cutting-edge technology, both in the olive grove and in the mill, but we still export a significant part of our production without our own brand. This limits the ability of national companies to capture added value.
I believe the future lies in increasing the weight of exports under strong and differentiated Portuguese brands, capable of enhancing not only the product but also the origin, quality, and identity of Portuguese olive oil. This evolution would allow for greater added value, reduce dependence on fluctuations in the international market, and make the sector less vulnerable to price volatility.
Virgin olive oil will fall to €5,07/liter at the end of 2025, after a period of strong inflationary pressure. From the retail and consumer perspective, this price adjustment is good news. But what is the impact on producers' margins?
The decline is mainly due to a less negative harvest in Spain – the world's largest producer. After two years marked by sharp production drops due to drought and adverse weather conditions, the recovery to a harvest considered average brought greater product availability to the market and, consequently, a correction in international prices.
From the retail and consumer perspective, this adjustment is naturally positive because it reduces the inflationary pressure felt in recent years. However, for producers, the impact is more challenging, especially because this price reduction occurs in a context where production costs continue to follow an inverse trend. Energy, labor, fertilizers, packaging, and financial costs remain at high levels, squeezing production margins.
Nevertheless, it is important to note that current prices generally remain at a level that provides some sustainability and security to the sector, especially for the most efficient producers and modern olive grove models with higher productivity. Obviously, those who will be feeling the most pressure are mainly traditional olive grove producers with lower productivity, who have significantly higher unit costs and less capacity to absorb market fluctuations. In these cases, a sharper drop in prices could compromise profitability and increase pressure on the economic viability of some farms.
Portugal produces over 90% extra virgin olive oil – the highest rate in the world. However, this high quality is not always reflected in the final price for the consumer. What is preventing Portuguese olive oil from being recognized and priced as a premium product in international markets?
This fact demonstrates the enormous investment made by the sector in technology, modernization, and technical knowledge, both in olive groves and in olive mills. However, this superior quality does not always translate into the final price paid by the international consumer, and this happens because there is still a gap between the quality we produce and the commercial strength with which we present ourselves in foreign markets.
Portugal produces excellent olive oils, but has focused primarily on producing well and less on communicating, positioning, and commercially enhancing that quality to the end consumer. A significant portion of the production continues to be exported in bulk, often ending up marketed under foreign brands, which prevents Portugal from capturing all the added value associated with the product.
For Portuguese olive oil to be truly recognized as a premium product, it is essential to strengthen the international presence of Portuguese brands and create a stronger narrative around the origin, authenticity, sustainability, and tradition of Portuguese olive growing.
Differentiation and brand building are identified as critical factors for sustaining margins. What concrete examples of premium positioning are working in the sector? And how has the large retail sector responded to this value-added logic?
The most successful examples of premium positioning in the olive oil sector are precisely those that have managed to go beyond purely productive logic and create an emotional and identity-based connection with the consumer. Today, markets increasingly value products with origin, authenticity, history, and purpose, and that is where some olive oil brands have managed to differentiate themselves.
Large retailers, in turn, have been gradually adapting to this logic of added value. For many years, olive oil was treated primarily as a promotional product and highly price-sensitive. Today, retailers are beginning to realize that there is a segment of consumers willing to pay more for quality and differentiation. This has led to an increased presence of premium ranges on the shelves, greater emphasis on differentiated olive oils, and even the development of more segmented categories within the product line. However, strong promotional pressure continues to exist in the sector, especially in more general ranges, which often hinders the sustained increase in the product's value.
The modernization of the Alentejo region as a production hub is evident. But to what extent is this technological transformation accessible to all producers, including small, traditional olive growers?
It is important to ensure that this modernization is inclusive, without a doubt. Technology is becoming increasingly accessible, and there are now simpler and more economical solutions that can also help small producers gain efficiency and sustainability.
Furthermore, traditional Portuguese olive groves have enormous differentiating value; they may not be able to compete on productivity alone, but they can assert themselves through authenticity, biodiversity, native varieties, and sustainability. The future of the sector must involve combining technological innovation with the appreciation of Portugal's traditional olive-growing heritage.
The agreement between the European Union and India opens access to a market of more than 1,47 billion consumers. In practical terms, what changes for Portuguese exporters? What tariff barriers are removed and what export volumes are expected?
With the signing of the agreement, tariffs on olive oil imports will drop from 45% to 0% within five years, so the projected growth is significant. According to a study by AICEP, "EU-India Free Trade Agreement: Opportunities for Portuguese companies," the Indian olive oil market is expected to reach $253 million by 2030. As Portugal is a major producer, it is important to anticipate this growth to gain market share against current and future exporters.
Indian consumers have a tradition of consuming other vegetable oils. How does Portuguese olive oil position itself in this market – as a premium niche product, as a healthy alternative, or as a culinary ingredient to be introduced into local habits?
In India, annual olive oil consumption is around 1.700 tons, a relatively low level considering the size of the country. Compared to Portugal, this is equivalent to about 2% of our average consumption.
Historically, olive oil in India did not enter the market through food, but rather through personal care and therapeutic uses. Embedded in a culture deeply marked by alternative medicine practices, oils have always played a central role, and olive oil ended up gaining prominence, especially in this context.
Nevertheless, this scenario does not preclude significant growth, as olive oil is beginning to gain recognition for its health benefits. Considering that the Indian market is dominated by other cooking oils, investment in promotion and marketing will be crucial to unlocking this potential.
“In Asia, besides India, markets such as China, Japan, and South Korea stand out. These are countries where per capita consumption is still relatively low, but where there is a growing interest in healthy food and gourmet products .”
Besides India, what other markets are on the sector's radar for diversifying destinations and reducing dependence on traditional European markets?
In Asia, besides India, markets such as China, Japan, and South Korea stand out. These are countries where per capita consumption is still relatively low, but where there is a growing interest in healthy food and gourmet products . South Korea, for example, has shown a very interesting evolution in the consumption of quality olive oil and could be a relevant market for more differentiated Portuguese brands.
The United States of America continues to be a priority market, not only because of its size, but also because American consumers increasingly value products associated with the Mediterranean diet, sustainability, and quality. It is a market where Portuguese olive oil still has significant room to grow in terms of brand awareness and premium positioning.
The Alentejo region faces increasing water pressure. How is the olive oil sector responding to this challenge? What technologies or water management models are being adopted?
The sector is fully aware of this reality and, precisely for this reason, has been investing heavily in increasingly efficient and sustainable technologies and management models. Today, a large part of modern olive groves uses highly efficient drip irrigation systems, which allow the plant to receive only the necessary water, at the right time and with minimal losses.
Simultaneously, precision agriculture technologies have been adopted, with soil moisture sensors, weather stations, satellite imagery and now, it is hoped, artificial intelligence tools capable of monitoring the olive grove's water needs in real time.
There is also a growing concern for more sustainable agronomic practices, such as improving soil structure, maintaining vegetation cover, increasing organic matter, and techniques that promote water retention in the soil and reduce evaporation.
Climate change has a direct impact on production – the 2025/2026 season is expected to reach 160 tons, below the previous cycle. How is the sector preparing for greater climate variability without compromising competitiveness?
The sector is preparing for this new reality through strong investment in technology, efficiency, and agronomic adaptation. In recent years, Portuguese olive growing has become much more resilient thanks to the modernization of olive groves, the professionalization of producers, and the transformative impact of Alqueva, which brought greater water security to the Alentejo region. Today, producers are increasingly resorting to precision agriculture, sensors, climate monitoring, and advanced irrigation systems to optimize resources and anticipate risks.
Efficient water management has become absolutely central, especially in a context of more frequent droughts and extreme temperatures. The 25/26 campaign was a prime example of this, and thanks to the optimization of water resources, the sector managed to minimize the impact, and we expect to see a decrease of only 10% compared to 24/25.
Environmental sustainability is increasingly becoming a purchasing criterion in the European market. Is Portuguese olive oil successfully communicating its sustainable practices to international consumers and distributors?
The sector has been evolving significantly in this area, but I believe there is still a long way to go in terms of communicating and promoting sustainable practices among international consumers.
In reality, much of modern Portuguese olive growing already incorporates very advanced practices in terms of water efficiency, resource management, environmental impact reduction, and technological innovation. The problem is that we often do better than we manage to communicate. Today, European consumers increasingly value these issues, and Portuguese olive oil does indeed have very strong arguments in this area; however, we have failed in this dissemination. We need to be better at communicating our attributes to the end consumer.
One of the congress panels was dedicated to artificial intelligence in the agricultural decision-making process. In which areas is AI already being used in olive growing, and what is the concrete impact on productivity and risk management?
Artificial intelligence is beginning to play an increasingly important role in olive growing, especially in the most modern and technologically advanced farms. Thanks to the strong modernization of the sector in recent decades, Portugal is in a very favorable position to integrate these tools into the agricultural decision-making process. This will be the next step for our sector to remain at the forefront of technology in the field and in extraction.
In olive groves, we believe it will have a strong impact on monitoring plantations through sensors, satellite imagery, and drones, allowing for real-time tracking of plant water status, vegetative development, nutritional needs, and early signs of stress and disease.
In olive mills, it can help optimize the extraction process by automatically adjusting parameters such as temperature or beating time according to the olive variety and its stage of ripeness. Furthermore, through image analysis systems, it may be possible to automatically assess the health status and ripeness of the olives upon arrival at the mill, allowing for the separation of batches and their allocation to different product profiles.
In the context of the congress's communication, it was mentioned that AI technologies "need to be rapidly brought to the heart of the sector." What is the main obstacle to this adoption? Is it a matter of digital literacy, access to funding, or the sector's culture?
I believe the main challenge lies not in a single factor, but above all in the combination of these three. In more modern and professionalized operations, adoption can be relatively quick because there is greater scale, more prepared technical teams, and a data-driven management culture.
However, a significant portion of the sector continues to be comprised of smaller or more traditional structures, where the introduction of these technologies may generate some resistance, either due to complexity or the difficulty in assessing the immediate return on investment.
The 9th National Olive Oil Congress brought together more than 30 speakers to discuss the themes of efficiency, AI, and value creation. What central message emerged from the congress, both for the sector and for the country?
The National Olive Oil Congress established itself as a privileged space for sharing ideas, experiences, and contacts. By bringing together different stakeholders from the sector, as well as experts from other areas, it promoted the circulation of knowledge and encouraged the adoption of innovative solutions, both in production and marketing. Several success stories in these areas were presented, with the aim of inspiring participants to reflect and question how they too could contribute to making a difference.
Expectations surrounding the event proved quite positive, with strong involvement from the sector and an open and constructive discussion about the role of new digital tools. It became clear that data management will be increasingly crucial for decision-making, and the congress helped to demystify and bring these solutions closer to producers.
The message that remained was, above all, one of mobilization and unity. The olive oil sector has clearly demonstrated an enormous capacity for adaptation and evolution, but it is currently experiencing a moment of transformation in which it is essential that everyone feels like an active part of this journey. More than deepening internal differences, the focus should be on what unites the sector: valuing Portuguese olive oil, reinforcing the commitment to quality, and maintaining an open attitude towards innovation and development. Only in this way will it be possible to continue growing sustainably and ensure that the entire supply chain benefits from this progress.